JPMorgan Raises SpaceX Price Target to $500 as Quarterly Revenue Beats Estimates
| Shelf | Ethereum & Altcoins |
|---|---|
| Date in | |
| Readers | 957 |
JPMorgan lifted its SpaceX target to $500 after revenue and earnings beat estimates, while analyst views and growth assumptions varied.

SpaceX’s quarterly results prompted a sharp reset in one Wall Street analyst’s expectations: JPMorgan’s Doug Anmuth raised his 12-month share-price target from $240 to $500. The change came alongside a revenue forecast of $254 billion for 2027 and a higher estimate for computing capacity. Those projections signal how much future growth investors are being asked to price in, while the company’s latest results provide a more immediate test of its expanding business.
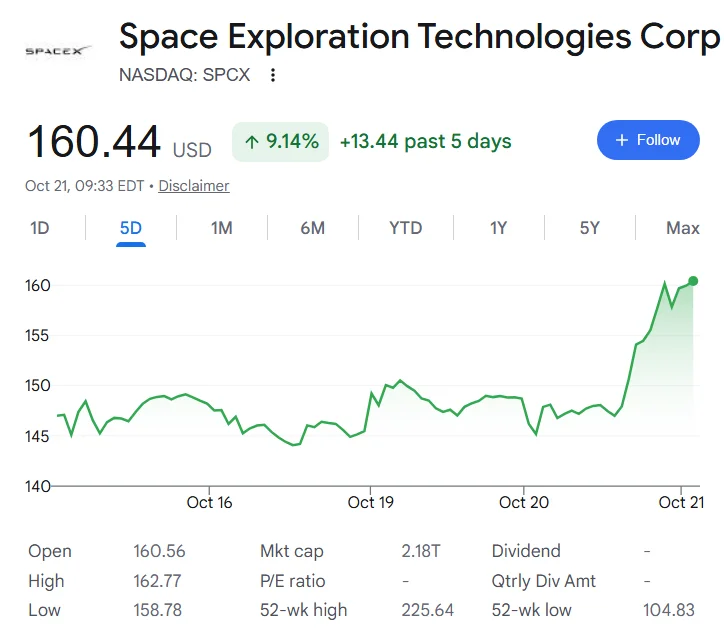
Anmuth kept his positive rating. At the reported share price of $160.44, the new $500 target implied a 211.64% gain over 12 months, compared with the 49.59% implied by his earlier $240 target. These are analyst estimates, not reported company results or guaranteed outcomes. The size of the revision makes the assumptions behind future revenue and capacity central to understanding the call.
The changes followed SpaceX’s third-quarter report, released after the market closed on Tuesday, October 20. Revenue reached $14.58 billion, up from $7.81 billion in the second quarter and above analysts’ $12.72 billion estimate. Earnings per share were $0.45, compared with an analyst forecast of $0.13 and a second-quarter loss of $0.09 per share. The company therefore exceeded expectations on both measures cited in the report.
Analyst targets span a wide range
JPMorgan’s revision was the most optimistic among the changes reported that morning. Thirteen analysts revisited their views on SpaceX shares on October 21, and eleven assigned a positive rating. That broad tilt did not mean their estimates were aligned: the published targets ranged from a modest increase to a projected decline.
Barclays analyst Anthony Valentini raised his target from $254 to $300, making him the second-most optimistic analyst in the group described. Susquehanna’s Charles Minervino retained a positive rating but made a much smaller adjustment, lifting his estimate from $173 to $176. KeyBanc’s Michael Leshock and Piper Sandler’s Alexander Potter both assigned neutral ratings. Potter’s $140 target implied a 12.74% decline over the next 12 months.
That spread matters because a strong quarter can support different conclusions about what comes next. Analysts may agree that results exceeded expectations while disagreeing about how much future growth is already reflected in a share price. The $500 estimate sits at the bullish end of the range described here; the $140 estimate shows that at least one analyst saw room for a lower valuation. The ratings and targets describe analysts’ views at that time, not a shared forecast of what the company will deliver.
Starlink and AI drive the growth assumptions
Two figures stood out beyond the headline revenue and earnings beats. Starlink’s user base reached 13.6 million, while reported AI sales rose to $7.56 billion. These figures point to different sources of activity within SpaceX’s broader business: connectivity subscriptions on one side and computing or AI-related revenue on the other.
The AI figure needs context. Roughly $3 billion of it was described as likely tied to a data-center rent agreement with Anthropic, reported earlier in the year. That qualification matters when interpreting the total: the number does not necessarily represent a single, uniform stream of AI product sales. The source does not break down the remaining AI-related revenue or give details that would show how recurring each component is.
JPMorgan also doubled its 2027 revenue projection to $254 billion and raised its computing-capacity estimate to 10 gigawatts. Capacity is a measure of potential computing resources, while revenue reflects sales recognized by the company; neither figure alone explains the investment, operating costs, utilization, or timing needed to reach the other. The source provides the revised estimates, but not a detailed breakdown of the assumptions behind them. That leaves the path from current results to those longer-term numbers as a key uncertainty.
What the quarter does and does not establish
The second-quarter-to-third-quarter revenue increase and the earnings surprise give analysts fresh evidence of near-term business growth. Starlink’s user count and AI-related sales add further detail about where that activity is coming from. But one reported quarter cannot by itself establish whether the same pace will continue, and the article does not provide segment-level margins or a full account of the costs associated with the reported growth.
The report also says JPMorgan viewed a possible SpaceX–Tesla merger positively. It gives no further details on the idea, its structure, or its status, so the point is best understood as part of the analyst’s outlook rather than a confirmed company development.
SpaceX shares rose more than 8% in overnight trading after the results, while the analyst revisions followed the report. The combination of a revenue beat, higher earnings per share, and growth in Starlink and AI-related sales helps explain the optimistic reaction. The more consequential question for the forecasts is whether the company can sustain that growth and expand computing capacity toward 10 gigawatts. The quarter strengthened the case for higher expectations, but the 2027 figures remain projections whose assumptions will need to be tested against subsequent results.


